Measuring Investment Losses Against the Market: A Miami Investor’s Guide
Key Takeaways: Market-adjusted damages measure investment losses by comparing an account’s actual performance to a reasonable benchmark index over the same period, rather than simply subtracting withdrawals from deposits. This can reveal harm that an out-of-pocket calculation misses, particularly when markets rose while a mismanaged Miami portfolio stagnated or declined. It tends to fit claims involving churning, unauthorized trading, unsuitable concentration, or margin-driven liquidations, though arbitrators retain discretion to accept, modify, or reject a proposed benchmark and need not explain their reasoning. Customer claims against FINRA member firms generally proceed under the FINRA Rule 12000 series nationwide, while Florida’s Chapter 517 may supply additional remedies and a limited Securities Guaranty Fund backstop available only in narrow circumstances. Challenges may arise over benchmark selection, causation during downturns, incomplete records, ratification, and timeliness. Strong documentation and a defensible benchmark matter, and collectability often deserves as much attention as the size of the theoretical claim.
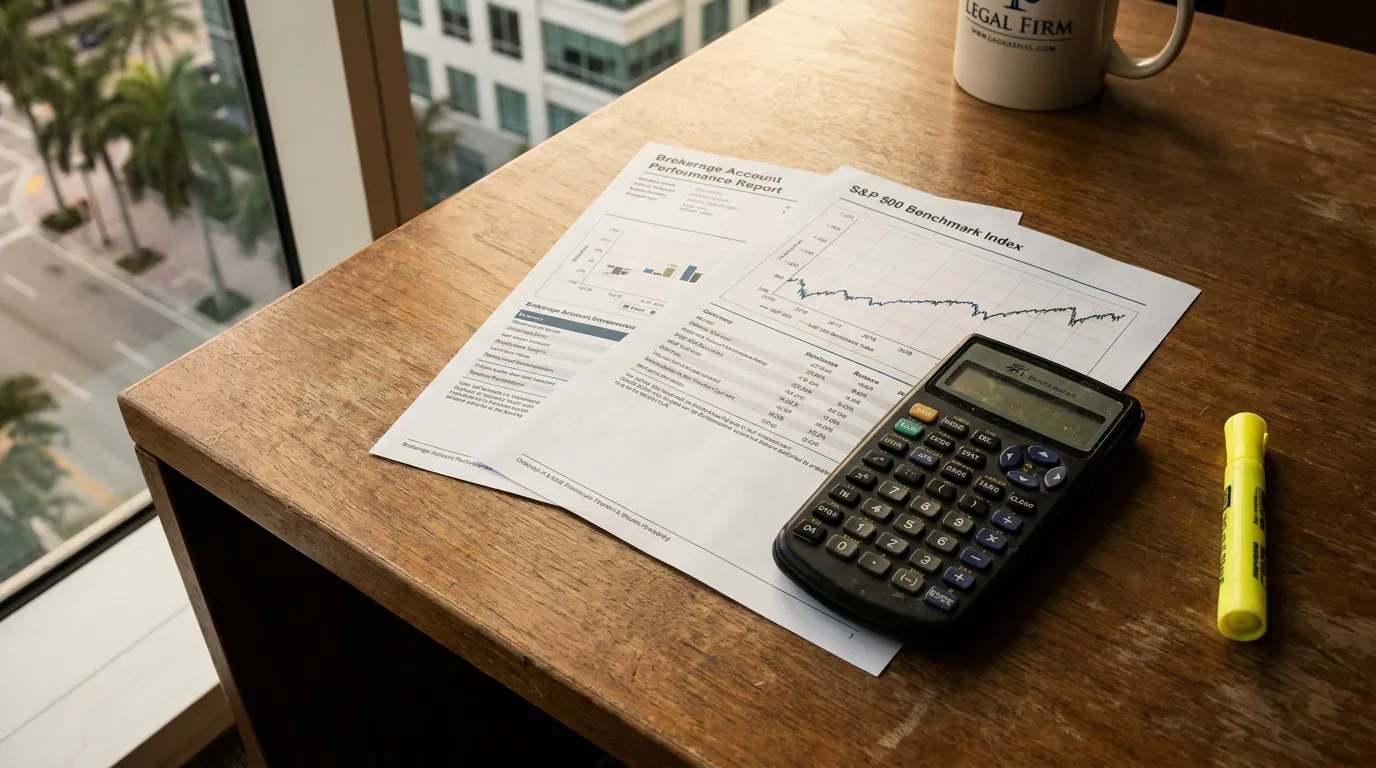
When a broker’s misconduct damages a portfolio, the raw account balance rarely tells the whole story. Market-adjusted damages ask: what would this portfolio reasonably be worth today if the broker had not mishandled it, measured against a comparable benchmark index over the same period? For Miami investors, this matters because a simple out-of-pocket calculation may understate real harm when markets rose while a mismanaged account stagnated or fell.
If you are weighing whether your losses support a claim, the team at Kaplan Rothstein Prüss Peraza, P.A can review your account records and discuss how damages might be framed. Call (888) 578-6255 or reach out through our contact page to start that conversation.
How Arbitrators Approach Damages Calculation in Investor Claims
Understanding the different damages models can be central to presenting a stronger claim. Practitioner literature commonly identifies out-of-pocket loss, well-managed portfolio, and market-adjusted approaches. These are analytical frameworks rather than models mandated by any FINRA rule or Florida statute, and which fits depends on the facts, the account’s stated objectives, and available records.
Arbitration panels are not bound to a single formula. FINRA materials describe arbitrators as having broad authority to fashion appropriate relief, including monetary damages, which may support alternative models where the evidence justifies them. Panels also are not generally required to itemize how they calculated an award. That discretion may create room for a well-supported market-adjusted theory, but outcomes remain fact-dependent and are never assured.
Out-of-Pocket Loss
This is generally the simplest and often most conservative measure. It compares what an investor put in against what remains or was returned. This model can leave real harm uncompensated when the broader market advanced substantially during the alleged mismanagement period.
Well-Managed Portfolio
This analysis asks what a prudently invested account, consistent with the customer’s actual objectives, might have produced. It tends to appear in unsuitability and improper allocation cases, generally requiring documentary evidence of stated risk tolerance, income needs, and time horizon, plus expert testimony to support the assumed alternative portfolio.
Market-Adjusted Damages
This approach measures loss relative to a benchmark index or general market movement over the relevant holding period. The theory is that absent the misconduct, funds would have participated in ordinary market performance consistent with the customer’s objectives. Benchmark selection, time period, and cash flow timing may all become contested, and panels may accept, modify, or reject a proposed benchmark.
Why Market Adjusted Damages Investor Losses Analysis Fits Certain Miami Claims
Market-adjusted damages tend to be most persuasive when misconduct kept money out of the market it belonged in, or trapped it in something unsuitable while comparable assets appreciated. Typical patterns include concentrated positions ignoring a retiree’s income needs, churning that eroded principal through commissions, unauthorized trading that abandoned a documented strategy, and margin-driven liquidations locking in losses at the worst moment. In each scenario, the gap between actual and benchmark performance can be substantial, though the claimant still bears the burden of tying that gap to the broker’s conduct.
This methodology is generally national rather than a creature of Florida law. A Miami claimant, a West Palm Beach family office, and a New York trust beneficiary would typically pursue the same theories under the same rules, though substantive state law and choice-of-law provisions can differ. Local geography tends to affect hearing logistics and counsel selection more than the damages framework itself.
💡 Pro Tip: Preserve every monthly statement, confirmation, new account form, and written communication with your broker. Benchmark comparisons depend on accurate transaction dates and amounts, and gaps in the record often narrow the damages theories realistically available.
The FINRA Rules That Govern Where and How You Present Damages
Customer claims against FINRA member firms generally proceed under the FINRA Rule 12000 series, the Code of Arbitration Procedure for Customer Disputes. The Code of Arbitration Procedure applies nationwide, so a Miami investor faces the same procedural architecture as a claimant anywhere else. FINRA Rule 12200 generally requires a member firm to arbitrate a customer dispute arising from its business activities when a written agreement so provides or the customer requests arbitration, a threshold question that often determines the forum before any damages discussion begins.
FINRA Rule 12302 governs filing and service of the initial Statement of Claim, and Rule 12303 governs the respondent’s answer. The statement of claim must specify the relevant facts and remedies requested, which is generally where a market-adjusted theory should be framed rather than left as a vague reference to losses. Rule 12206 separately bars claims submitted more than six years after the events giving rise to the dispute, an eligibility limit distinct from any applicable statute of limitations. For more, see our overview of FINRA arbitration for Miami investors.
| Damages Model | Core Question | Common Fit |
|---|---|---|
| Out-of-pocket | What did I lose in raw dollars? | Simple misrepresentation claims |
| Well-managed portfolio | What would a suitable portfolio have earned? | Unsuitability, allocation errors |
| Market-adjusted | How did I fare against a benchmark? | Churning, unauthorized trading, concentration |
Florida Law That Runs Alongside Your Arbitration Claim
Florida’s securities regime generally supplements, rather than replaces, the FINRA damages analysis. Chapter 517 of the Florida Statutes, the Florida Securities and Investor Protection Act, governs registration of securities, dealers, and investment advisers, along with anti-fraud provisions reaching transactions in Florida. Fla. Stat. § 517.211, addressing remedies for unlawful sales, generally provides a purchaser with rescission and recovery of consideration paid plus interest, less any income received, or damages where the investor no longer owns the security, applying only to enumerated violations of the chapter. That section carries its own limitations and notice requirements, so timing should be evaluated early. These state-law remedies may complement arbitration damages theories, subject to specific facts and defenses.
Florida also maintains a limited collection backstop. Under Fla. Stat. § 517.131(2)(a), the Chief Financial Officer establishes a Securities Guaranty Fund to provide monetary relief to victims of securities violations under the chapter who are entitled to damages or restitution and cannot recover fully from the wrongdoer. Access is narrow: it generally requires an unsatisfied final judgment or restitution order tied to a violation of § 517.07 or § 517.301, and a confirmed arbitration award can qualify as a "final judgment." Statutory eligibility conditions, exclusions, and per-claim and aggregate payment caps under § 517.141 all apply. The fund itself is capped: Fla. Stat. § 517.131(2)(b) provides that if the balance exceeds $1.5 million, transfers of assessment fees must be discontinued at the end of that registration year and may not resume unless disbursements reduce the balance below $1 million. Realistic expectations matter, because an award and a collected award are not the same thing.
What This Means for Collectability
Investors sometimes prevail and still face difficulty recovering. Firm insolvency, individual broker judgments, and limited insurance coverage can all constrain actual recovery. Any serious market adjusted damages investor losses lawyer evaluation should consider not only the size of the theoretical claim but the respondents’ realistic ability to pay.
Practical Obstacles in Presenting Portfolio Damages
Market-adjusted claims may invite pointed challenges, and anticipating them can improve credibility with a panel. Common friction points include:
- Benchmark disputes, where the defense argues a more conservative index better matches stated objectives
- Causation gaps, particularly during broad market downturns where losses may be attributed to conditions rather than conduct
- Incomplete records, which may weaken calculations dependent on precise dates and amounts
- Comparative conduct arguments, including claims that the investor approved, ratified, or failed to mitigate transactions
- Timeliness questions, including the Rule 12206 six-year eligibility limit and separately applicable limitations and repose periods, which may be interpreted narrowly and apply differently depending on the claim asserted
💡 Pro Tip: Write down a chronology while your memory is fresh, including when you first noticed something wrong and what your broker said about it. Timing questions often surface early, and contemporaneous detail can be more persuasive than later reconstruction.
Frequently Asked Questions
1. Is a market-adjusted calculation available in every FINRA arbitration Miami claim?
Not necessarily. Panels retain broad discretion over the type and amount of damages awarded and may find another model better matches the evidence. Whether this approach fits depends on the account’s documented objectives, the nature of the misconduct, and the quality of the transaction record.
2. Which benchmark index applies to my portfolio damages analysis?
There is no mandated benchmark under FINRA rules or Florida law. Selection generally turns on the investor’s stated objectives and risk tolerance, and the choice is frequently contested. A well-supported comparison typically explains why the selected index reflects how the account should reasonably have been positioned.
3. Does Florida law or FINRA law control my damages calculation?
Both may be relevant, and FINRA rules are not themselves law. The FINRA 12000 series generally governs the arbitration forum and procedure, while Chapter 517 and common law may supply the substantive claims and remedies asserted within the arbitration. How the two interact is fact-specific and often shaped by the claims pled and any choice-of-law provision in the account agreement.
4. Can I still bring a broker negligence claim if I signed everything my broker sent me?
Possibly. Signed documents matter and firms often rely on them heavily, but they do not automatically defeat claims involving unsuitable recommendations, undisclosed risks, or misrepresentations. A panel may find the disclosure inadequate relative to the conduct, though signed acknowledgments can meaningfully weaken a claim.
5. What if my losses happened during a general market decline?
Broad declines may complicate causation but do not necessarily bar recovery. The analysis generally focuses on whether the specific portfolio suffered harm beyond what a suitably managed account would have experienced, since losses attributable solely to market conditions are typically not recoverable. This is a situation where comparative benchmarking may be informative.
Bringing the Damages Picture Into Focus
Market-adjusted damages may give Miami investors a way to describe harm that a simple deposit-minus-withdrawal calculation misses. The methodology sits within FINRA’s national arbitration framework, alongside Florida’s Chapter 517 remedies and its limited guaranty fund. Outcomes generally depend on documentation, a defensible benchmark, and a clear causal link between the broker’s conduct and the shortfall, and results always turn on the particular facts of the account.
To discuss how your losses might be measured and what recovery avenues may realistically be available, connect with Kaplan Rothstein Prüss Peraza, P.A today. Reach our team at (888) 578-6255 or request a case review here.
Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.